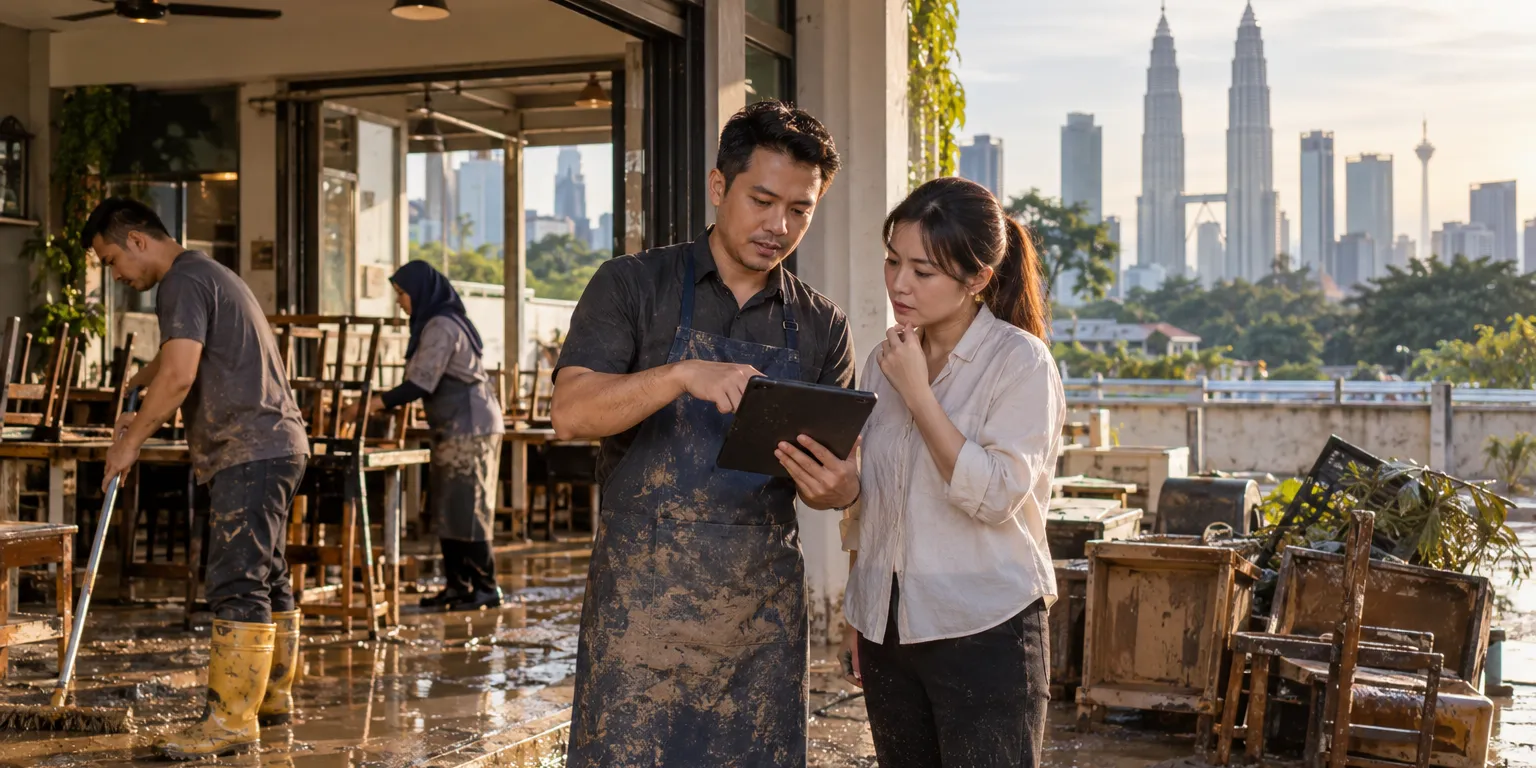
When a flood tears through your premises, small business emergency funding is often the difference between reopening and closing for good. Most owners discover this only after disaster strikes, when cash is draining fastest and options seem few. Knowing the landscape before you need it changes the outcome.
Malaysia's monsoon season regularly brings severe flooding to states such as Kelantan, Terengganu and Johor, and the December 2021 floods remain among the costliest in the country's history. Every such event leaves thousands of small enterprises without stock, equipment or working capital. Yet help does exist, and much of it is government-backed.
In 2026, the support landscape is clearer than many owners realise. SME Corporation Malaysia's SINAR programme opened applications in June 2026, subject to available funds. Bank Negara Malaysia's Relief and Adaptation Facility also offers financing after major floods; each channel has its own eligibility rules.
In this blog, we discuss the first steps after a disaster, the 2026 SINAR financing schemes, guarantee-backed bank loans, other relief channels, and how to prepare your business for the next emergency.
What can emergency funding for small businesses cover after a disaster?
Emergency funding is designed to restore operations, not to patch old debts. In practice it covers working capital, repairs, replacement equipment and restocking — the costs that decide whether you can open next week.
Lenders and agencies look first at whether the money restarts your business. A clear picture of what counts as recovery spending makes your application far easier to assess.
Typical uses include:
- Restocking inventory lost to water or fire damage
- Repairing or replacing machinery, fittings and vehicles
- Paying wages and rent while trading is suspended
- Covering supplier deposits so production can restart
Note the limits. For example, SJPP's working capital and automation guarantee schemes exclude refinancing facilities already granted by participating financial institutions. Officials want to see new money going into recovery, not into old obligations. Keep this in mind when you plan how much to ask for.
What Should You Do Before Applying for Any Relief Funding?
Lenders assess applications using supporting evidence, so your first priority is documentation. Gather proof of the damage and your trading history before you approach anyone.
The sequence matters. Complete evidence can help avoid delays. Ask your insurer about its documentation requirements before cleanup begins, where it is safe to do so.
- Photograph and video all damage before cleaning up.
- Notify your insurer in writing and keep copies of everything.
- Contact your bank early to discuss restructuring or a payment moratorium.
- Secure your financial statements, tax records and SSM filings.
- Confirm your MSME status so you qualify for SME-only schemes.
Lost records are a common setback after floods and fires. If your ledgers were destroyed, the best accounting firm in Kuala Lumpur can help you reconstruct statements for your lender's review. Acting promptly can help you prepare before limited funds are exhausted.
Post-Disaster Funding Checklist
| Task | Why It Matters | Where to Go |
|---|---|---|
| Photograph and video all damage | Evidence supports insurance claims and financing applications | Your insurer and lender |
| Confirm your MSME status | Unlocks SME-only schemes such as SINAR and guarantee schemes | SME Corporation Malaysia |
| Prepare financial statements | Lenders need proof of revenue and obligations | Your accountant |
| Approach participating banks | Guarantee cover of up to 80% eases collateral demands | SJPP participating banks |
| Keep SSM filings current | Lenders verify your registration before approving facilities | SSM |
What Is SINAR and Which Schemes Are Open in 2026?
SINAR is SME Corporation Malaysia's support package for micro, small and medium enterprises (MSMEs) facing economic shocks and unforeseen events. Applications opened in June 2026 and are subject to available funds; confirm current availability with the relevant provider.
SME Corporation Malaysia's SINAR programme exists precisely for moments when cash flow breaks, making it one route to small business emergency funding after a flood or other shock. It channels financing and business support through appointed partners, and its 2026 terms include a concession: several schemes carry reduced rates for approvals granted this year.
Three financing schemes sit under the programme. SINAR is not a dedicated disaster fund, so check whether your business and intended use of financing meet the relevant scheme's criteria.
1. Soft Financing Scheme for SMEs (SFSME 2.0)
This scheme lends between RM50,000 and RM5 million for fixed assets and working capital. The rate is 5% to 6% per annum on the monthly outstanding balance, with 5% applying to approvals in 2026. Malaysian Industrial Development Finance Berhad (MIDF) implements it, and applications are made online.
2. Business Accelerator Programme (BAP)
BAP offers Shariah-compliant and conventional financing through a digital platform. Term financing reaches up to RM500,000 over 36 months, at 5% per annum for 2026 approvals and 6% to 8% from 2027. Invoice and purchase order financing reaches up to RM1.5 million over six months, priced at 0.5% to 0.7% per month.
3. PRESTIGE 2.0 Financing Scheme
PRESTIGE 2.0 targets SMEs in high-growth strategic industries. It offers term financing up to RM1 million and invoice financing up to RM500,000, but applications are temporarily closed pending fund availability. Term financing is charged at 3% per annum with a rebate of up to 30% subject to conditions, while invoice financing costs 0.5% per month.
How Do Government Guarantee Schemes Help SMEs Without Collateral?
A government guarantee may help an eligible SME obtain financing when collateral is limited. Cover can reach 80% of an eligible facility, subject to the scheme and lender's assessment.
Syarikat Jaminan Pembiayaan Perniagaan Berhad (SJPP) administers government guarantee schemes, including six working capital and automation schemes. Their framework is available to participating financial institutions until 31 December 2035, or until the guarantee limit is fully used.
Eligibility follows the national MSME definition. Manufacturing companies qualify with sales turnover not exceeding RM50 million or no more than 200 full-time employees, while other sectors qualify at RM20 million or 75 full-time employees. At least 51% of shares must be held by Malaysians.
You apply at any participating bank, not to SJPP directly. After the bank approves your facility, it submits the papers for guarantee cover. The guarantee fee is 1.0% per annum for the general scheme and 0.75% for the others, payable in advance upon approval.
Companies may borrow up to RM10 million by combining schemes or banks. Main-board listed companies and subsidiaries of main-board listed companies, multinationals, government-linked companies, Syarikat Menteri Kewangan Diperbadankan and state-owned enterprises are excluded.
SINAR Financing Schemes and 2026 Terms
| Scheme | Financing Amount | Rate | Partner |
|---|---|---|---|
| SFSME 2.0 | RM50,000 – RM5 million | 5%–6% p.a.; 5% for 2026 approvals | MIDF |
| BAP Term Financing | Up to RM500,000 (up to 36 months) | 5% p.a. in 2026; 6%–8% from 2027 | microLEAP |
| BAP Invoice / PO Financing | Up to RM1.5 million (up to 6 months) | 0.5%–0.7% per month | microLEAP |
| PRESTIGE 2.0 | Up to RM1 million term; up to RM500,000 invoice | 3% p.a. term; 0.5% per month invoice | Funding Societies; applications temporarily closed |
Which Other Emergency Relief Options Can SMEs Turn To?
Beyond SINAR and guarantee-backed bank loans, three further channels regularly help disaster-hit businesses: banks themselves, insurers, and industry bodies with their own assistance programmes.
Each channel suits a different stage of recovery. For an unresolved insurance dispute, litigation lawyers in Kuala Lumpur can advise on possible next steps.
1. Commercial banks and Bank Negara Malaysia
Your existing bank is a useful early contact for discussing restructuring or a moratorium. Bank Negara Malaysia's Relief and Adaptation Facility offers up to RM1 million each for relief financing after major floods and for flood adaptation. Ask a participating bank about eligibility, availability and its credit assessment. Bank Negara Malaysia, the central bank, supervises the financing sector and publishes guidance on borrower rights and complaint channels when negotiations stall.
2. Insurers and business interruption cover
If you hold business interruption insurance, the claim may cover lost income during closure, not just physical damage. If a claim is delayed or rejected, review the insurer's reasons and your policy terms before considering legal advice.
3. Industry associations and other government schemes
Chambers of commerce, trade associations and state development agencies sometimes run their own relief assistance after major floods. Service businesses planning longer-term capacity can also study the soft loan scheme for the service sector as a complement to immediate disaster relief.
SJPP Government Guarantee Schemes Compared
| Scheme | Who It Serves | Financing Limit | Guarantee Fee |
|---|---|---|---|
| WCGS | SMEs in all sectors | RM100,000 – RM10 million | 1.0% p.a. |
| WCGS-SU | Start-ups trading 6 months to 2 years | RM50,000 – RM500,000 | 0.75% p.a. |
| WCGS-B | At least 51% Bumiputera-owned | RM100,000 – RM3 million | 0.75% p.a. |
| WCGS-X | At least 30% export turnover | RM100,000 – RM10 million | 0.75% p.a. |
| WCGS-W | At least 51% Malaysian women-owned | RM100,000 – RM1 million | 0.75% p.a. |
| ADGS | Automation and digitalisation projects | RM100,000 – RM10 million | 0.75% p.a. |
How Can Your Business Prepare Before the Next Disaster Strikes?
Current registrations, digital records and relevant MSME documentation can help businesses prepare a relief application and avoid delays.
The best time to prepare is before the monsoon, not during it. For ownership continuity, private trust setup services in Malaysia may be worth considering. Four habits can help.
1. Register your MSME status in advance
SME Corporation Malaysia certifies that your company meets the national MSME definition set by the Government's development council. Many schemes ask for this status, so holding the certificate already removes one step from an emergency application.
2. Keep records digital and filings current
Lenders verify your profile with the Companies Commission of Malaysia (SSM) before approving facilities. If you operate as a sole proprietorship or partnership, note that SJPP's six working capital and automation guarantee schemes cap financing at RM1 million for your structure; other schemes have different terms.
3. Review insurance and build a cash buffer
Check annually whether your policy covers flood and business interruption, not just fire. Even a modest reserve covering two months of rent and wages buys time while applications are processed.
4. Plan for continuity and succession
An owner's illness after a disaster can paralyse a company as surely as water damage. Discuss whether a trust or other succession arrangements suit your ownership structure.
Conclusion
Disaster recovery funding in Malaysia now runs through identifiable doors: document everything first, weigh the SINAR schemes on their 2026 terms, then use guarantee-backed bank facilities where collateral is thin. Insurers, banks and industry bodies complete the picture.
The practical order is straightforward. Secure evidence, confirm your MSME status, approach a participating bank, and keep registrations and records current so nothing slows you down.
When you need small business emergency funding after a flood, fire or storm, these channels offer a realistic path back to trading. Malaysia Brands exists to help homegrown companies through exactly these moments — share your recovery story with us, browse our guides, or reach us through our contact page.
Rebuild With a Community Behind You
Tell Malaysia Brands how your business is recovering. We feature homegrown companies and connect you with resources that build visibility and trust.
Frequently Asked Questions
SINAR is SME Corporation Malaysia's support package for micro, small and medium enterprises facing economic uncertainty and unforeseen events. It provides access to financing schemes such as SFSME 2.0, BAP and PRESTIGE 2.0. Applications opened in June 2026 and remain open until committed funds are exhausted.
Through SJPP, the Government of Malaysia guarantees up to 80% of eligible credit facilities provided by participating banks. For SJPP's six working capital and automation schemes, the framework is available until 31 December 2035 or until the limit is fully utilised, and guarantee fees range from 0.75% to 1.0% per annum, payable in advance. Other schemes have different terms. The guarantee protects the lender; the borrower must still repay the loan.
Yes, under the start-up variant of the Working Capital Guarantee Scheme. The business must have been operating between 6 months and 2 years, and a mandatory site visit is part of the assessment. The financing limit for start-ups is RM50,000 to RM500,000.
No. SJPP's six working capital and automation guarantee schemes exclude refinancing of facilities already granted by the same or another participating financial institution. The schemes fund working capital and capital expenditure for recovery and growth, not old obligations.
Yes. Under SJPP's six working capital and automation guarantee schemes, sole proprietors and partnerships may access up to RM1 million in credit facilities, while SMEs may borrow up to RM10 million by combining schemes and participating banks. Other schemes have different limits. Formalising your structure can therefore expand your funding headroom.
Malaysia Brands
Author
We are dedicated to promoting and celebrating business brands in Malaysia. We share the inspiring success stories of homegrown brands, highlighting their achievements and growth.